Valuation cheat sheet
Important
This documentation is for Odoo 19 or later. Discover why we changed.
Costing Methods
Odoo supports 3 costing methods configured in accounting’s settings and, optionally, the product’s category.
- Standard Cost: fixed unit cost, updated manually
Operation
Unit Cost
Qty On Hand
Delta Value
Inventory Value
$10
0
$0
Receive 8 @$10
$10
8
+8×$10
$80
Receive 4 @$16
$10
12
+4×$10
$120
Deliver 10
$10
2
-10×$10$20
Receive 2 @$9
$10
4
+2×$10
$40
- Average Cost: weighted average of all units
Operation
Unit Cost
Qty On Hand
Delta Value
Inventory Value
$0
0
$0
Receive 8 @$10
$10
8
+8×$10
$80
Receive 4 @$16
$12
12
+4×$16
$144
Deliver 10
$12
2
-10×$12$24
Receive 2 @$6
$9
4
+2×$6
$36
- FIFO: first in, first out
Operation
Unit Cost
Qty On Hand
Delta Value
Inventory Value
$0
0
$0
Receive 8 @$10
$10
8
+8×$10
$80
Receive 4 @$16
$12
12
+4×$16
$144
Deliver 10
$16
2
-8×$10-2×$16$32
Receive 2 @$6
$11
4
+2×$6
$44
Note
Removal strategies also support LIFO and FEFO, but they only impact which product is first picked, not the valuation method. For example, you can pick using LIFO, but using average cost for valuation, as LIFO is not allowed by IFRS.
Inventory vs Accounting
The Inventory app keeps track of the inventory value in real time as you receive and deliver goods. The reporting menu lets you analyze inventory quantities and values by company, location, product, and more.
The Accounting app updates accounts when you receive invoices or bills. Even though receipts and invoices differ, it’s not practical for accountants to post journal entries for every inventory movement. So, they post a closing entry to account for the difference between what has been invoiced and received/delivered. This closing process happens usually once a year for SMEs, or once a month for larger companies.
Accounting |
Inventory |
|
|---|---|---|
Purchase Order |
/ |
/ |
Receipt |
/ |
✓ |
Vendor Bill |
✓ |
/ |
Sales Order |
/ |
/ |
Customer Invoice |
✓ |
/ |
Delivery |
/ |
✓ |
Closing Entry |
✓ |
/ |
Accounting Methods
There are two accounting practices on how to maintain your accounts, defined in , under the Inventory Valuation section:
Periodic: Post vendor bills as expenses by nature, and update stock valuation in the closing entry by reducing expenses (stock variation). This is the best practice in Europe.
Perpetual: Post vendor bills as assets (stock valuation), report expenses when goods are sold (cost of goods sold). This is the best practice in countries that follow Anglo-Saxon accounting, like the USA and India.
Stock Account on the product’s category
Stock Variation on the stock account
Expense/Cost of Goods Sold on the product/category
Inventory Adjustment on the Inventory Loss location (optional, recommended for Anglo-Saxon accounting)
Expense on the stock account (for perpetual Continental accounting only)
See also
Inventory valuation: For more detailed instructions on the accounting aspects of configuring inventory valuation.
Valuation of stock movements and inventory operations: For more information about the impact of stock movements and adjustments on inventory valuation.
EU Periodic |
EU Perpetual |
US Periodic |
US Perpetual |
|
|---|---|---|---|---|
ADJUSTMENT |
Stock |
Stock |
||
LOSS |
Shrinkage |
|||
BILL |
Expense |
Stock |
COGS |
Stock |
Payable |
Payable |
Payable |
Payable |
|
INVOICE |
Expense |
COGS |
||
Stock |
Stock |
|||
Income |
Income |
Income |
Income |
|
Receivable |
Receivable |
Receivable |
Receivable |
|
Closing |
Stock |
Stock |
Stock |
Stock |
[1] |
Variation |
Expense |
Variation |
Variation |
[2] |
LOSS |
Shrinkage |
||
[3] |
Variation |
|||
Expense |
Inventory valuation - Accounting valuation
Inventory valuation lost, only if an account is set on the loss location
Accounting valuation end of period - Valuation beginning of period
Accounting Entries
Choose a standard:
Continental (Expenses = Purchase Expenses)
Anglo-Saxon (Expenses = Cost of Goods Sold)
Choose an accounting method:
Periodic: focuses on expenses by nature
Perpetual: focuses on inventory value
Activate operations to see the impact:
Initial Inventory (Goods for Resale $50)
Supplier Goods Reception (PO $50, Bill $50)
Supplier Bill (PO $50, Bill $50)
Supplier Goods Reception (PO $48, Bill $50)
Supplier Bill (PO $48, Bill $50)
Customer Shipping (SO $100, Invoice $100, Good Value $50)
Customer Invoice (SO $100, Invoice $100, Good Value $50)
Manufacturing Order (Finished Product at $52, Component at $50)
Inventory Loss (Scrap $30)
Closing
Bill To Receive
Invoices To Be Issued
Billed Not Received
Invoiced Not Delivered
Inventory Valuation
Debit |
Credit |
Balance |
|
|---|---|---|---|
1 Equity and Liabilities |
|||
2 Fixed Assets |
|||
3 Stock (Current Assets) |
|||
300000 Inventory Raw Materials |
|||
320000 Work in Progress |
|||
330000 Inventory Finished Goods |
|||
340000 Inventory Goods Purchase for Resale |
|||
4 Receivables and Payables |
|||
400000 Customers |
|||
411000 VAT Recoverable |
|||
414000 Income Receivable |
|||
440000 Suppliers |
|||
444000 Invoices to Be Received |
|||
451000 VAT Payable |
|||
490000 Deferred Charges |
|||
493000 Deferred Income |
|||
5 Financial Accounts and Cash |
|||
6 Expenses |
|||
600000 Raw Materials |
|||
600200 Cost of Finished Goods |
|||
604000 Goods for Resale |
|||
609000 Decrease (Increase) in Stocks of Raw Materials |
|||
609400 Decrease (Increase) in Stocks of Goods Purchased for Resale |
|||
7 Revenues |
|||
700000 Sales |
|||
712000 Increase (Decrease) in Stocks of Work in Progress |
|||
713000 Increase (Decrease) in Stocks of Finished Goods |
|||
General Balance for Inventory Initial Value |
Debit |
Credit |
Balance |
|
|---|---|---|---|
1 Assets |
|||
101401 Bank |
|||
110100 Inventory |
|||
110101 Raw Materials Inventory |
|||
110102 Manufactured Products Inventory |
|||
110400 Cost of Production |
|||
110600 Inventory Variations |
|||
121000 Accounts Receivable |
|||
121200 Uninvoiced Receivable |
|||
128000 Prepaid Expenses |
|||
131000 Tax Paid |
|||
2 Liabilities |
|||
211000 Accounts Payable |
|||
211100 Bills to Receive/Goods Received Not Invoiced |
|||
212000 Deferred Revenue |
|||
251000 Tax Received |
|||
3 Equity |
|||
303000 Common Stock |
|||
4 Revenue |
|||
400000 Product Sales |
|||
5 Expenses |
|||
500000 Cost of Goods Sold |
|||
530000 Price Difference |
|||
609100 Inventory Loss Expense |
|||
609000 Miscellaneous Expenses |
|||
General Balance for Inventory Initial Value |
Journal Entries Configuration
Choose a standard:
Continental (Expenses = Purchase Expenses)
Anglo-Saxon (Expenses = Cost of Goods Sold)
Choose an accounting method:
Periodic: focuses on expenses by nature
Perpetual: focuses on inventory value
Activate operations to see the impact:
Initial Inventory (Goods for Resale $50)
Supplier Goods Reception (PO $50, Bill $50)
Supplier Bill (PO $50, Bill $50)
Supplier Goods Reception (PO $48, Bill $50)
Supplier Bill (PO $48, Bill $50)
Customer Shipping (SO $100, Invoice $100, Good Value $50)
Customer Invoice (SO $100, Invoice $100, Good Value $50)
Manufacturing Order (Finished Product at $52, Component at $50)
Inventory Loss (Scrap $30)
Closing
Bill To Receive
Invoices To Be Issued
Billed Not Received
Invoiced Not Delivered
Inventory Valuation
Account |
Debit |
Credit |
|---|---|---|
340000 Inventory Goods Purchase for Resale |
50 |
|
General Balance for Inventory Initial Value |
50 |
Configuration
Stock Account: defined on the product category
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
50 |
|
General Balance for Inventory Initial Value |
50 |
Configuration
Stock Account: defined on the product category
Explanation
In a periodic inventory valuation, goods’ receipts are not directly posted in the accounting.
The inventory value is updated when entries are generated from Inventory Valuation report at closing.
Explanation
In a perpetual inventory valuation, goods receipts are not directly posted in the accounting.
The inventory value is updated:
when the invoice/bill is posted
when entries are generated from Inventory Valuation report at closing
Account |
Debit |
Credit |
|---|---|---|
604000 Goods for Resale |
50 |
|
440000 Suppliers |
54.5 |
|
411000 VAT Recoverable |
4.5 |
Configuration
Account Payable: defined on the supplier contact
Tax Account: defined on the account from the Purchase Taxes set on the product
Expense Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
340000 Inventory Goods Purchase for Resale |
50 |
|
440000 Suppliers |
54.5 |
|
411000 VAT Recoverable |
4.5 |
Configuration
Stock Account: defined on the product category
Account Payable Account: defined on the supplier contact
Tax Account: defined on the account from the Purchase Taxes set on the product
Account |
Debit |
Credit |
|---|---|---|
500000 Cost of Goods Sold |
50 |
|
211000 Accounts Payable |
54.5 |
|
131000 Tax Paid |
4.5 |
Configuration
Account Payable: defined on the supplier contact
Tax Account: defined on the account from the Purchase Taxes set on the product
Expense Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
50 |
|
211000 Accounts Payable |
54.5 |
|
131000 Tax Paid |
4.5 |
Configuration
Account Payable: defined on the supplier contact
Tax Account: defined on the account from the Purchase Taxes set on the product
Expense Account: defined on the product/product category
Explanation
In a periodic inventory valuation, goods shipments are not directly posted in the accounting.
The inventory value is updated when entries are generated from Inventory Valuation report at closing.
Explanation
In a perpetual inventory valuation, goods shipments are not directly posted in the accounting.
The inventory value is updated:
when the invoice/bill is posted
when entries are generated from Inventory Valuation report at closing
Account |
Debit |
Credit |
|---|---|---|
400000 Customers |
109 |
|
451000 VAT Payable |
9 |
|
700000 Sales |
100 |
Configuration
Account Receivable Account: defined on the customer contact
Tax Account: defined on the account from the Sales Taxes set on the product
Income Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
340000 Inventory Goods Purchase for Resale |
50 |
|
604000 Goods for Resale |
50 |
|
400000 Customers |
109 |
|
451000 VAT Payable |
9 |
|
700000 Sales |
100 |
Configuration
Stock Account: defined on the product category
Expense/COGS Account: defined on the product/product category
Account Receivable Account: defined on the customer contact
Tax Account: defined on the account from the Sales Taxes set on the product
Income Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
121000 Accounts Receivable |
109 |
|
251000 Tax Received |
9 |
|
400000 Product Sales |
100 |
Configuration
Account Receivable Account: defined on the customer contact
Tax Account: defined on the account from the Sales Taxes set on the product
Income Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
50 |
|
500000 Cost of Goods Sold |
50 |
|
121000 Accounts Receivable |
109 |
|
251000 Tax Received |
9 |
|
400000 Product Sales |
100 |
Configuration
Stock Account: defined on the product category
Expense/COGS Account: defined on the product/product category
Account Receivable Account: defined on the customer contact
Tax Account: defined on the account from the Sales Taxes set on the product
Income Account: defined on the product/product category
Explanation
In a periodic inventory valuation manufacturing orders are not directly posted in the accounting.
The inventory value is updated when entries are generated from Inventory Valuation report at closing.
Explanation
No ‘Cost of Production’ account is set on the production location, therefore variations in inventories of manufactured goods and components will be recorded at closing.
Account |
Debit |
Credit |
|---|---|---|
110102 Manufactured Products Inventory |
52 |
|
110400 Cost of Production |
52 |
|
110101 Raw Materials Inventory |
50 |
|
110400 Cost of Production |
50 |
Configuration
Stock Account for manufactured product: defined on the product category
Stock Account for component: defined on the product category
Cost of Production Account: defined on the production location
Explanation
In a periodic inventory valuation, inventory adjustments are not directly posted in the accounting.
The inventory value is updated when entries are generated from Inventory Valuation report at closing.
Explanation
No ‘Inventory Loss’ account is set on the inventory loss location, therefore variations in inventories coming from inventory adjustments will be recorded at closing.
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
30 |
|
609100 Inventory Loss Expense |
30 |
Configuration
Stock Account: defined on the product category
Inventory Adjustment Account: defined on the inventory loss location
Account |
Debit |
Credit |
|---|---|---|
444000 Invoices to Be Received |
50 |
|
604000 Goods for Resale |
50 |
|
444000 Invoices to Be Received |
48 |
|
604000 Goods for Resale |
48 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that expenses are recognized in the period in which they are incurred, regardless of when cash is paid.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Configuration
Expense Account: defined on the product/product category
GRNI Account: defined when generating accrual entries from ‘Bill To Receive’
Account |
Debit |
Credit |
|---|---|---|
444000 Invoices to Be Received |
50 |
|
604000 Goods for Resale |
50 |
|
444000 Invoices to Be Received |
48 |
|
604000 Goods for Resale |
48 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that expenses are recognized in the period in which they are incurred, regardless of when cash is paid.
They are reverted after the period we are closing.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Configuration
Expense Account: defined on the product/product category
GRNI Account: defined when generating accrual entries from ‘Bill To Receive’
Account |
Debit |
Credit |
|---|---|---|
211100 Bills to Receive/Goods Received Not Invoiced |
50 |
|
500000 Cost of Goods Sold |
50 |
|
211100 Bills to Receive/Goods Received Not Invoiced |
48 |
|
500000 Cost of Goods Sold |
48 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that expenses are recognized in the period in which they are incurred, regardless of when cash is paid.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Configuration
Expense Account: defined on the product/product category
GRNI Account: defined when generating accrual entries from ‘Bill To Receive’
Account |
Debit |
Credit |
|---|---|---|
211100 Bills to Receive/Goods Received Not Invoiced |
50 |
|
110600 Inventory Variations |
50 |
|
211100 Bills to Receive/Goods Received Not Invoiced |
48 |
|
110600 Inventory Variations |
48 |
Explanation
Accrual entries are adjusting journal entries made at the end of an accounting period to ensure that revenues/expenses are recognized in the period in which they are earned/incurred, regardless of when cash is received / paid.
They are reverted after the period we are closing.
From a stock point of view, it also enables us to specify a part of the origin of stock variations (between Accounting Stock and Inventory Stock) recorded from the Inventory Valuation report.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Configuration
Inventory Variation Account: defined on the used Stock Account for the product category
GRNI Account: defined when generating accrual entries from ‘Bill To Receive’
Account |
Debit |
Credit |
|---|---|---|
414000 Income Receivable |
100 |
|
700000 Sales |
100 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that revenues are recognized in the period in which they are earned, regardless of when cash is received.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Configuration
Revenue Account: defined on the product/product category
Uninvoiced Receivable Account: defined when generating accrual entries from ‘Invoices To Be Issued’
Account |
Debit |
Credit |
|---|---|---|
414000 Income Receivable |
100 |
|
700000 Sales |
100 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that revenues are recognized in the period in which they are earned, regardless of when cash is received.
They are reverted after the period we are closing.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Configuration
Revenue Account: defined on the product/product category
Uninvoiced Receivable Account: defined when generating accrual entries from ‘Invoices To Be Issued’
Account |
Debit |
Credit |
|---|---|---|
121200 Uninvoiced Receivable |
100 |
|
400000 Product Sales |
100 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that revenues are recognized in the period in which they are earned, regardless of when cash is received.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Configuration
Revenue Account: defined on the product/product category
Uninvoiced Receivable Account: defined when generating accrual entries from ‘Invoices To Be Issued’
Account |
Debit |
Credit |
|---|---|---|
121200 Uninvoiced Receivable |
100 |
|
400000 Product Sales |
100 |
|
110600 Inventory Variations |
50 |
|
500000 Cost of Goods Sold |
50 |
Explanation
These accrual entries are adjusting journal entries made at the end of an accounting period to ensure that revenues/expenses are recognized in the period in which they are earned/incurred, regardless of when cash is received/paid.
From a stock point of view, it also enables us to specify a part of the origin of stock variations (between Accounting Stock and Inventory Stock) recorded from the Inventory Valuation report.
They are reverted after the period we are closing.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Configuration
Inventory Variation Account: defined on the used Stock Account for the product category
Uninvoiced Receivable Account: defined when generating accrual entries from ‘Invoices To Be Issued’
Revenue Account: defined on the product/product category
Expense/COGS Account: defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
490000 Deferred Charges |
50 |
|
604000 Goods for Resale |
50 |
|
490000 Deferred Charges |
50 |
|
604000 Goods for Resale |
50 |
Explanation
Billed Not Received are journal entries made during closing when a supplier bill is received before goods or services are received, so the amount is recorded as an asset until the expense is recognized.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is not done but the bill is received
Supplier Goods Reception (PO $48, Bill $50) is not done but the bill is received
Configuration
Expense Account: defined on the product/product category
Prepaid Expense Account: defined when generating entries from ‘Billed Not Received’
Account |
Debit |
Credit |
|---|---|---|
128000 Prepaid Expenses |
50 |
|
500000 Cost of Goods Sold |
50 |
|
128000 Prepaid Expenses |
50 |
|
500000 Cost of Goods Sold |
50 |
Explanation
Billed Not Received are journal entries made during closing when a supplier bill is received before goods or services are received, so the amount is recorded as an asset until the expense is recognized.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is not done but the bill is received
Supplier Goods Reception (PO $48, Bill $50) is not done but the bill is received
Configuration
Expense Account: defined on the product/product category
Prepaid Expense Account: defined when generating entries from ‘Billed Not Received’
Account |
Debit |
Credit |
|---|---|---|
128000 Prepaid Expenses |
50 |
|
110600 Inventory Variations |
50 |
|
128000 Prepaid Expenses |
50 |
|
110600 Inventory Variations |
50 |
Explanation
Billed Not Received are journal entries made during closing when a supplier bill is received before goods or services are received, so the amount is recorded as an asset until the expense is recognized.
From a stock point of view, it also enables us to specify a part of the origin of stock variations (between Accounting Stock and Inventory Stock) recorded from the Inventory Valuation report.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is not done but the bill is received
Supplier Goods Reception (PO $48, Bill $50) is not done but the bill is received
Configuration
Inventory Variation Account: defined on the used Stock Account for the product category
Prepaid Expense Account: defined when generating entries from ‘Billed Not Received’
Account |
Debit |
Credit |
|---|---|---|
493000 Deferred Income |
100 |
|
700000 Sales |
100 |
Explanation
Invoiced Not Delivered are journal entries made during closing when an invoice has been issued but goods or services are not delivered yet, so the amount has to be recorded as a liability until the revenue is earned.
They are reverted after the period we are closing.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is not done but the invoice is sent
Configuration
Revenue Account: defined on the product/product category
Deferred Revenue Account: defined when generating accrual entries from ‘Invoiced Not Delivered’
Account |
Debit |
Credit |
|---|---|---|
212000 Deferred Revenue |
100 |
|
400000 Product Sales |
100 |
|
110600 Inventory Variations |
50 |
|
500000 Cost of Goods Sold |
50 |
Explanation
Invoiced Not Delivered are journal entries made during closing when an invoice has been issued but goods or services are not delivered yet, so the amount has to be recorded as a liability until the revenue is earned.
From a stock point of view, it also enables us to specify a part of the origin of stock variations (between Accounting Stock and Inventory Stock) recorded from the Inventory Valuation report.
They are reverted after the period we are closing.
Related operation:
Customer Shipping (SO $100, Invoice $100, Good Value $50) is not done but the invoice is sent
Configuration
Inventory Variation Account: defined on the used Stock Account for the product category
Deferred Revenue Account: defined when generating accrual entries from ‘Invoiced Not Delivered’
Revenue Account: defined on the product/product category
Expense/COGS Account : defined on the product/product category
Account |
Debit |
Credit |
|---|---|---|
340000 Inventory Goods Purchase for Resale |
20 |
|
609400 Decrease (Increase) in Stocks of Goods Purchased for Resale |
20 |
|
330000 Inventory Finished Goods |
52 |
|
300000 Inventory Raw Materials |
50 |
|
713000 Increase (Decrease) in Stocks of Finished Goods |
52 |
|
609000 Decrease (Increase) in Stocks of Raw Materials |
50 |
Explanation
At closing, Inventory Valuation must be updated to reflect reality. This will be done by generating entries from the Inventory Valuation report. This will recognize value coming from operations such as the following ones:
Supplier Goods Reception (PO $50, Bill $50)
Supplier Goods Reception (PO $48, Bill $50)
Customer Shipping (SO $100, Invoice $100, Good Value $50)
Inventory Loss (Scrap $30)
Manufacturing Order (Finished Product at $52, Component at $50)
Configuration
Stock Account: defined on the product category
Inventory Variation Account: defined on the used Stock Account
Account |
Debit |
Credit |
|---|---|---|
340000 Inventory Goods Purchase for Resale |
18 |
|
604000 Goods for Resale |
18 |
|
330000 Inventory Finished Goods |
52 |
|
600200 Cost of Finished Goods |
52 |
|
300000 Inventory Raw Materials |
50 |
|
600000 Raw Materials |
50 |
|
609400 Decrease (Increase) in Stocks of Goods Purchased for Resale |
18 |
|
604000 Goods for Resale |
18 |
|
600000 Raw Materials |
50 |
|
609000 Decrease (Increase) in Stocks of Raw Materials |
50 |
|
600200 Cost of Finished Goods |
52 |
|
713000 Increase (Decrease) in Stocks of Finished Goods |
52 |
Explanation
At closing Accounting Stock and Inventory Stock must have the same value.
A difference could come from cases such as the ones listed below and this will be corrected thanks to the Inventory Valuation report closing entry.
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Inventory Loss (Scrap $30)
Manufacturing Order (Finished Product at $52, Component at $50)
At closing, an adjusting entry is created to ensure that the values are correctly recorded in the variation and expenses accounts according to continental accounting logic. Indeed, even though expenses are recorded according to the COGS logic of Anglo-Saxon accounting during the period, at closing the expenses recorded should represent what was actually purchased during this period.
The variation is known thanks to the calculation (Stock Account y - Stock Account y-1) for each of the following categories:
Purchased good for resale
Component
Finished product
Configuration
Expense Account: defined on the product/product category
Stock Account: defined on the product category
Inventory Variation Account: defined on the used Stock Account
Expense Account for adjusting entry: defined on the used Stock Account
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
50 |
|
500000 Cost of Goods Sold |
50 |
|
110100 Inventory |
30 |
|
609100 Inventory Loss Expense |
30 |
|
110102 Manufactured Products Inventory |
52 |
|
110400 Cost of Production |
52 |
|
110101 Raw Materials Inventory |
50 |
|
110400 Cost of Production |
50 |
Explanation
At closing, Inventory Valuation must be updated to reflect reality. This will be done by generating entries from the Inventory Valuation report. This will recognize value coming from operations such as the following ones:
Supplier Goods Reception (PO $50, Bill $50)
Supplier Goods Reception (PO $48, Bill $50)
Customer Shipping (SO $100, Invoice $100, Good Value $50)
Inventory Loss (Scrap $30)
Manufacturing Order (Finished Product at $52, Component at $50)
Configuration
Stock Account: defined on the product category
Inventory Variation Account: defined on the used Stock Account
Inventory Adjustment Account: defined on the Inventory Loss location
Cost of Production Account: defined on the Production location
Account |
Debit |
Credit |
|---|---|---|
110100 Inventory |
48 |
|
110600 Inventory Variations |
48 |
Explanation
At closing, Accounting Stock and Inventory Stock must have the same value.
A difference could come from cases such as the ones listed below and this will be corrected thanks to the Inventory Valuation report closing entry.
Related operations:
Supplier Goods Reception (PO $50, Bill $50) is done but no bill is received yet
Supplier Goods Reception (PO $48, Bill $50) is done but no bill is received yet
Customer Shipping (SO $100, Invoice $100, Good Value $50) is done but no invoice is sent yet
Configuration
Stock Account: defined on the product category
Inventory Variation Account: defined on the used Stock Account
Reporting
In Inventory
Open to view your current inventory level and valuation for each product, or to review historical data as of a previous date.

Unit cost
To check a product’s existing unit price updates and their origins, click on the product’s Unit Cost. In AVCO this allows you to understand how the currently used value was calculated.

Total value
To see all incoming quantities for which you still have a remaining quantity and the value used for their valuation, click on a product’s Total Value.
In AVCO or standard cost, the used value is always the current average unit cost.
In FIFO, remaining units from each previous incoming move retain their own individual valuation.
In FIFO or AVCO, remaining quantities from a previous incoming move can have their value adjusted if necessary: Select the incoming moves to be adjusted, click Actions, and then click Adjust Valuation. Enter the new Value and, optionally, a Description.

In Accounting
To view the difference between the accounting stock value and the current inventory value recorded thanks to the incoming moves with a remaining quantity, go to .
To generate a new accounting entry to review and post, click Generate Entry.

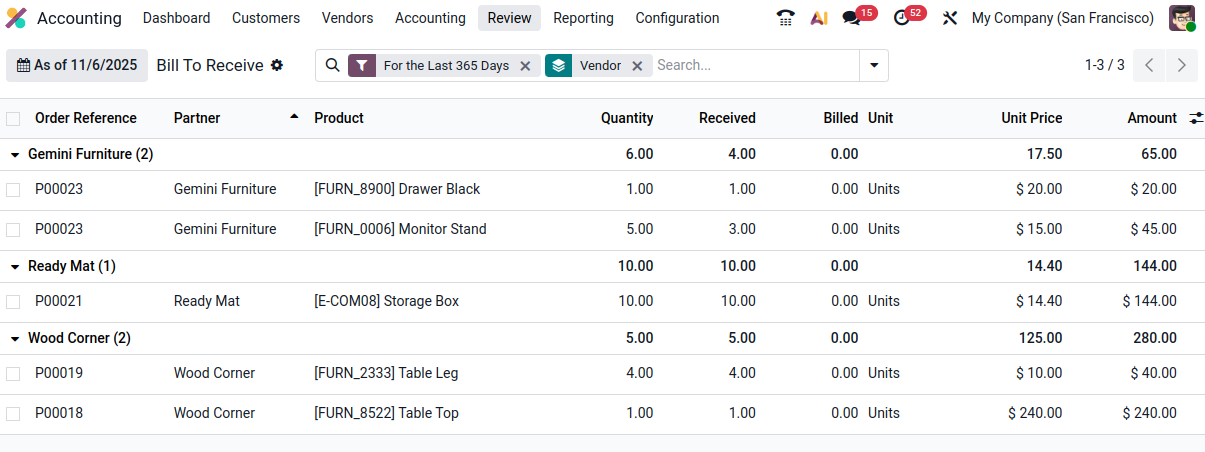
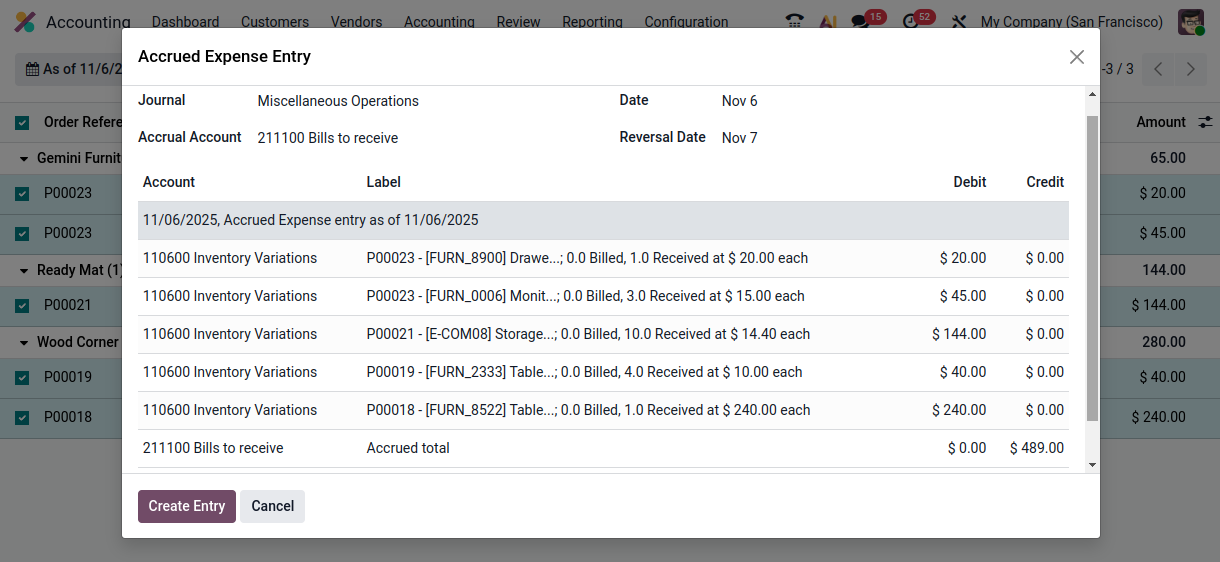
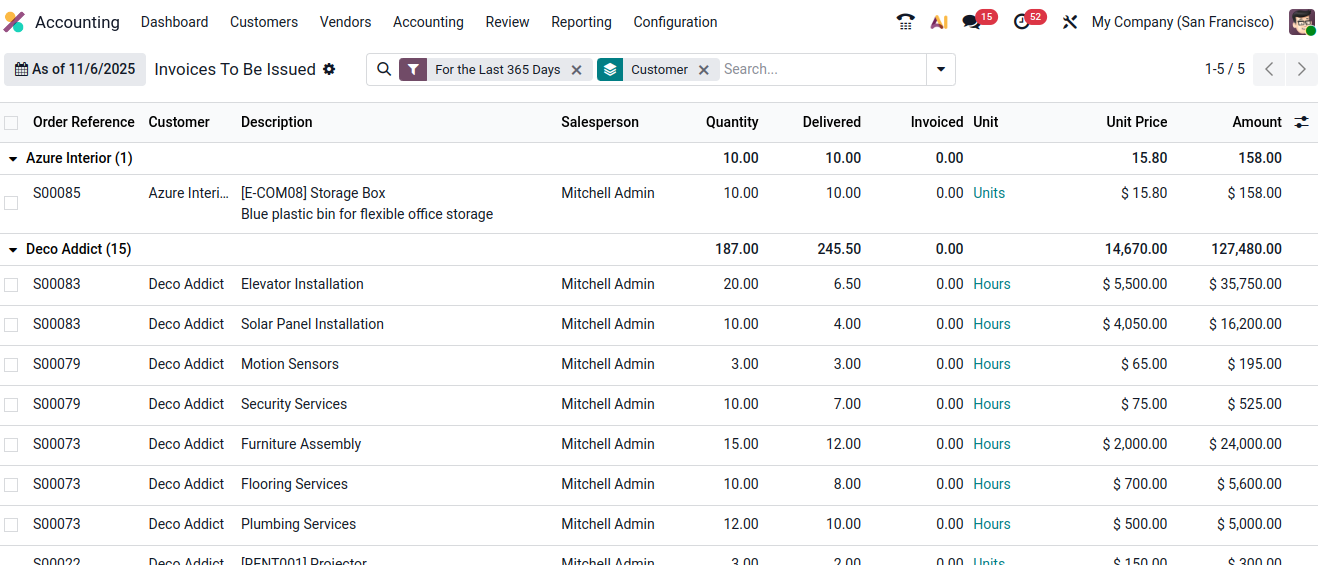
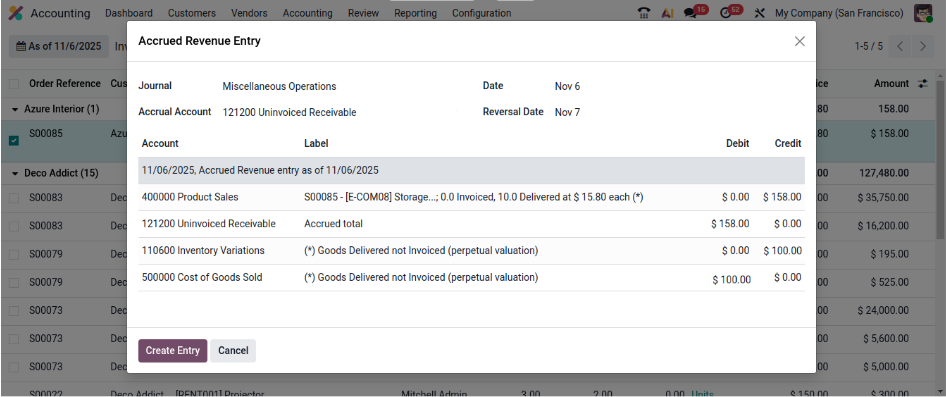
To view a list of sales and purchase orders for which accrual entries should be encoded, go to and select the relevant menu item (Bill To Receive, Invoices To Be Issued, Billed Not Received and Invoiced Not Delivered). Select the desired lines and click Create Accrual Entries.
With Anglo-Saxon perpetual accounting, this will also help to distribute recorded inventory variations to accounts such as Bills to Receive/GRNI or COGS as shown in the Accounting Entries and Journal Entries Configuration sections.
Changes in Odoo 19
Before Odoo 19, the Perpetual accounting method was implemented by posting real-time accounting entries at each stock movement. That created a lot of journal items in accounting, which was an issue for performance, general ledger clarity and auditability.
Since Odoo 19, the Perpetual method impacts the stock valuation account at the invoice level. The closing entry is then used to manage bills to receive, invoices to issue, deferred revenues, prepaid expenses, and other gaps between inventory values and accounting ones.
Odoo 18 |
Odoo 19 |
|
|---|---|---|
Periodic Continental |
Manual closing |
Automated closing |
Periodic Anglo-Saxon |
Not supported |
Fully supported |
Perpetual Continental |
Manual closing |
✓ |
Perpetual Anglo-Saxon |
Manual closing |
✓ |
Accounting valuation |
Requires inventory |
Accounting only |
Perpetual Entries |
Invoices + every moves |
Invoices + one closing |
Invoices to issue |
✗ |
✓ |
Prepaid expenses |
✗ |
✓ |
Bills to receive |
✗ |
✓ |
Deferred revenues |
✗ |
✓ |
Performance |
Slower |
Faster |
General ledger |
More journal entries |
Fewer journal entries |